Spinal Fusion Device Market Size and Growth 2026 to 2035
 Status Published
 Category Medical Devices


Content
Spinal Fusion Device Market: Size, Segmentation and 2035 Forecast
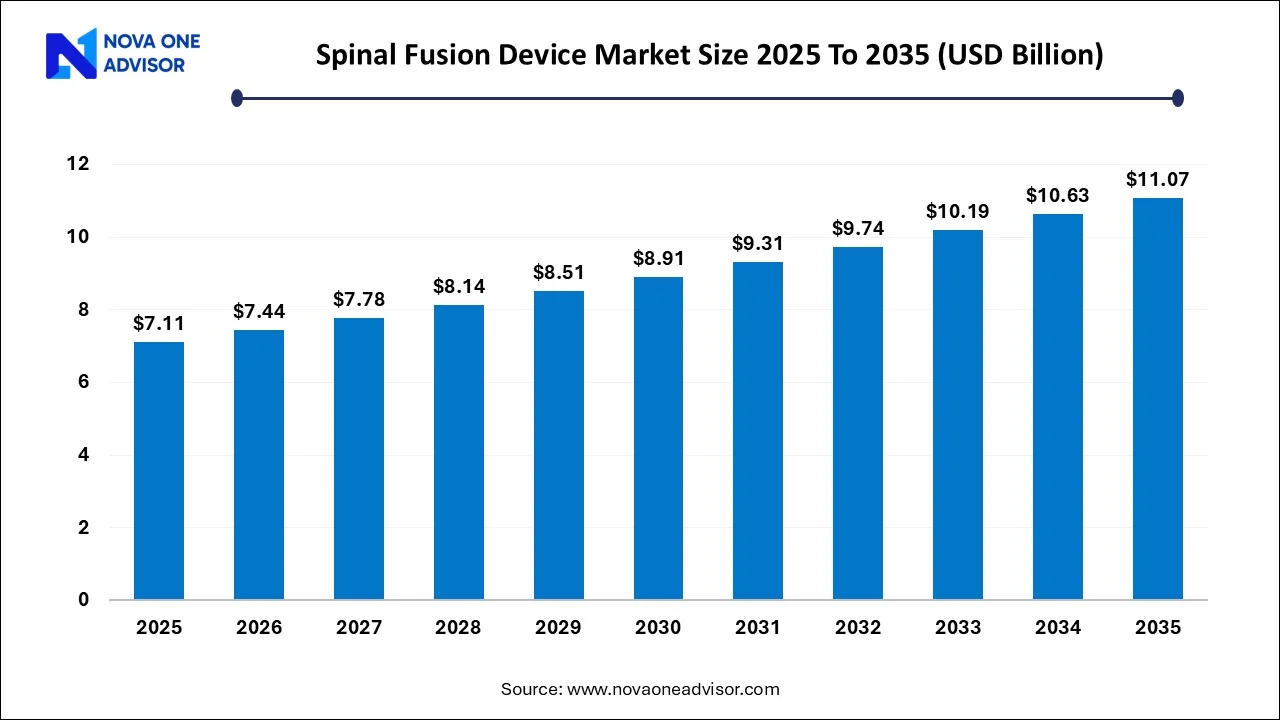
The global spinal fusion device market was valued at USD 7.11 billion in 2025 and is projected to reach approximately USD 11.07 billion by 2035, growing at a CAGR of 4.53% from 2026 to 2035.
Key Takeaways:
- The thoracolumbar devices segment dominated the market for spinal fusion devices and accounted for the largest revenue share of more than 55.0% in 2025.
- The Degenerative Disc Disease segment dominated the market for spinal fusion devices and accounted for the largest revenue share of over 42.0% in 2025.
- The minimally invasive surgery segment dominated the market for spinal fusion devices and accounted for the largest revenue share of 64.0% in 2025 reflecting increasing adoption of less invasive approaches in selected spinal fusion procedures.
- The hospitals dominated the market for spinal fusion devices and accounted for the largest revenue share of over 60.0% in 2025.
- North America dominated the spinal fusion devices market and accounted for the largest revenue share of over 43.0% in 2025.
Market Overview
The spinal fusion device market has emerged as a Spinal fusion devices are used to stabilize spinal segments during procedures intended to treat selected degenerative, traumatic, deformity-related, and instability conditions. Spinal fusion surgeries aim to correct deformities, treat Degenerative Disc Disease , fractures, and spinal instability by permanently connecting two or more vertebrae. Common spinal fusion systems include pedicle screws and rods, plates, and interbody fusion devices, with device selection varying by anatomy, indication, and surgical approach., cages, and plates to stabilize and support the spine during the healing process.
Advancements in biomaterials, minimally invasive surgical techniques, and image-guided navigation have significantly expanded the range of spinal fusion solutions available. An aging population and the prevalence of degenerative and other spinal disorders are important factors influencing demand for spinal fusion procedures. are key factors propelling market growth.
Moreover, the market has seen notable technological innovations such as Emerging technologies include 3D-printed implants and patient-specific implant designs. As healthcare systems prioritize outcomes and value-based care, .These developments are expanding the range of device options used in spinal fusion procedures.
Major Trends in the Market
-
Increasing adoption of minimally invasive spine surgery in selected procedures: Techniques that Selected minimally invasive approaches can reduce tissue disruption and may shorten hospital stays or recovery times compared with appropriate open procedures.
-
Adoption of Biologics and Bone Grafts: Advances in bone graft substitutes and biologic materials are expanding options for supporting fusion.
-
3D Printing and Patient-specific Implants: Customized implants designed for patient-specific anatomy are gaining adoption in selected spinal applications.
-
Integration of Navigation and Robotics: Navigation and robotic-assisted systems are increasingly used to support implant placement and surgical planning.
-
Growing Demand for Anterior and Lateral Approaches: Alternative surgical access points Anterior and lateral approaches can provide alternative access routes that may reduce posterior tissue disruption in appropriately selected procedures.
-
Focus on Motion Preservation Techniques: Development of dynamic stabilization devices to maintain natural spine movement.
Spinal Fusion Device Market Report Scope
| Report Coverage | Details |
| Market Size in 2026 | USD 7.44 Billion |
| Market Size by 2035 | USD 11.07 Billion |
| Growth Rate From 2026 to 2035 | CAGR of 4.53% |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Segments Covered | Product, Disease Type, Surgery, End-User, Region |
| Regional Scope | North America; Europe; Asia-Pacific; Central and Latin America; the Middle East & Africa (MEA) |
| Key Companies Profiled | Johnson & Johnson Services, Inc. (DePuy Synthes); Stryker; Zimmer Biomet; Orthofix Medical, Inc.; B. Braun Melsungen AG; Medtronic; NuVasive, Inc.; Globus Medical; ATEC Spine, Inc; Captiva Spine, Inc; SeaSpine; Spinal Elements, Inc.; Spine Wave, Inc.; Spineology, Inc.; Xtant Medical Holdings, Inc. |
By Product Insights
Thoracolumbar devices dominated the product segment. Thoracolumbar fusion devices, including anterior lumbar plates and pedicle screw and rod systems, are widely utilized to stabilize and correct deformities in the lower thoracic and lumbar spine. Given that Degenerative lumbar conditions are an important indication associated with spinal fusion procedures, demand for these devices remains high. Pedicle screw and rod systems, in particular, provide robust fixation and are widely used in posterior spinal fixation procedures. driving this segment's dominance.
Interbody fusion devices are the fastest-growing product segment. Interbody fusion devices, which replace degenerated intervertebral discs and restore disc height and spinal alignment, are witnessing rapid growth. Advances such as 3D-printed cage designs can support porous architectures intended to facilitate bone integration; clinical outcomes vary by device and indication. and post-surgical imaging clarity. As surgeons increasingly favor anterior and lateral approaches for interbody fusion, this segment's adoption is expected to outpace traditional fixation methods.
By Disease Type Insights
Degenerative Disc Disease dominated the disease type segment. Degenerative Disc Disease (DDD) is a leading indication for spinal fusion surgery. As intervertebral discs lose hydration and elasticity with age, they can cause pain, instability, and nerve compression. Spinal fusion may be considered for selected patients with symptomatic degenerative conditions when conservative management is insufficient and surgery is clinically appropriate.” to stabilize the affected segment and alleviate symptoms. Given the high prevalence of DDD in aging populations, its dominance in driving fusion procedures is unsurprising.
Complex deformities are the fastest-growing disease segment. Conditions like scoliosis, kyphosis, and other spinal deformities necessitate complex, multilevel spinal fusion procedures. Advances in 3D planning, patient-specific instrumentation, and intraoperative navigation are expanding planning and fixation options for complex deformity procedures. for deformity corrections. Increasing diagnosis rates, improved awareness, and access to surgical solutions are propelling growth in this specialized segment.
By Surgery Insights
Open surgery remains an established approach for complex spinal procedures, including selected multilevel and deformity cases. for spinal fusion for decades. It allows direct visualization of the surgical site, facilitating complex reconstructions, deformity corrections, and multilevel fusions. Despite growing interest in MISS, open surgery remains prevalent for extensive and complicated cases.
Minimally invasive spine surgery is the fastest-growing surgery segment. For selected procedures, minimally invasive approaches may achieve comparable clinical outcomes while reducing tissue disruption and, in some cases, hospital stay. As technological barriers decrease and surgeon training improves, more institutions are adopting MISS techniques for lumbar, thoracic, and cervical fusions. The trend towards value-based care further accelerates this shift, given MISS's shorter hospital stays and faster recoveries.
By End-user Insights
Hospitals dominated the end-user segment. Hospitals remain the primary centers for spinal fusion surgeries due to their comprehensive surgical capabilities, specialized personnel, and access to advanced imaging and intensive postoperative care facilities. The majority of complex spine surgeries, including multilevel fusions and deformity corrections, are conducted in hospital settings.
Specialty clinics are the fastest-growing end-user segment. The proliferation of specialized spine clinics and ambulatory surgical centers (ASCs) offering minimally invasive spine surgeries is a significant trend. These centers provide cost-effective, efficient care for single-level fusions and less complex procedures. Patient preference for outpatient settings with reduced waiting times and faster discharges is driving this segment's rapid growth.
By Regional Insights
North America dominated the spinal fusion device market. North America’s leadership is attributed to a high prevalence of spinal disorders, advanced healthcare infrastructure, and early adoption of innovative technologies. The United States, in particular, accounts for a substantial share due to high surgical volumes, favorable reimbursement policies, and the presence of key industry players such as Medtronic, Zimmer Biomet, and NuVasive. Moreover, a strong focus on R&D activities, clinical trials, and surgeon training programs supports market growth in the region.
Asia-Pacific is the fastest-growing region. Asia-Pacific is experiencing significant market expansion fueled by improving healthcare infrastructure, rising disposable incomes, and growing awareness about spinal health. Countries like China, India, and Japan are investing heavily in expanding their orthopedic and neurosurgical capabilities. Increasing healthcare expenditure, along with the rising burden of spine-related disorders among the aging population, is fostering demand for advanced spinal fusion devices in the region. Additionally, local manufacturing initiatives and government support are boosting the availability and affordability of these devices.
Companies Covered in the Analysis in the Spinal fusion device include:
- Johnson & Johnson Services, Inc. (DePuy Synthes)
- Stryker
- Zimmer Biomet
- Orthofix Medical, Inc.
- B. Braun Melsungen AG
- Medtronic
- NuVasive, Inc.
- Globus Medical
- ATEC Spine, Inc
- Captiva Spine, Inc
- SeaSpine
- Spinal Elements, Inc.
- Spine Wave, Inc.
- Spineology, Inc.
- Xtant Medical Holdings, Inc.
Segments Covered in the Report
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments This report analyzes historical data and forecasts revenue from 2026 to 2035. For this study, Nova One Advisor, Inc. segments the global spinal fusion device market by product, disease type, surgery, end user, and region.
Product
- Thoracolumbar Devices
- Anterior Lumbar Plates
- Pedicle Screw and Rods
- Others
- Cervical Fixation Devices
- Anterior Cervical Plates
- Hook Fixation Systems
- Others
- Interbody Fusion Devices
Disease Type
- Degenerative Disc Disease
- Complex Deformity
- Trauma & Fractures
- Others
Surgery
- Open spine surgery
- Minimally Invasive Spine Surgery
End-user
- Hospitals
- Specialty Clinics
- Others
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East & Africa (MEA)
FAQ's

Proceed to Buy
Instant PDF delivery on confirmation
Spinal Fusion Device Market Size to Hit USD 11.07 Billion by 2035
 Request Customization
 Download Sample
Get a Sample of this Report
Spinal Fusion Device Market