Spinal Traction Market Size, Share, and Trends 2026 to 2035
 Status Published
 Category Healthcare


Content
Spinal Traction Market Size and Growth 2026 to 2035
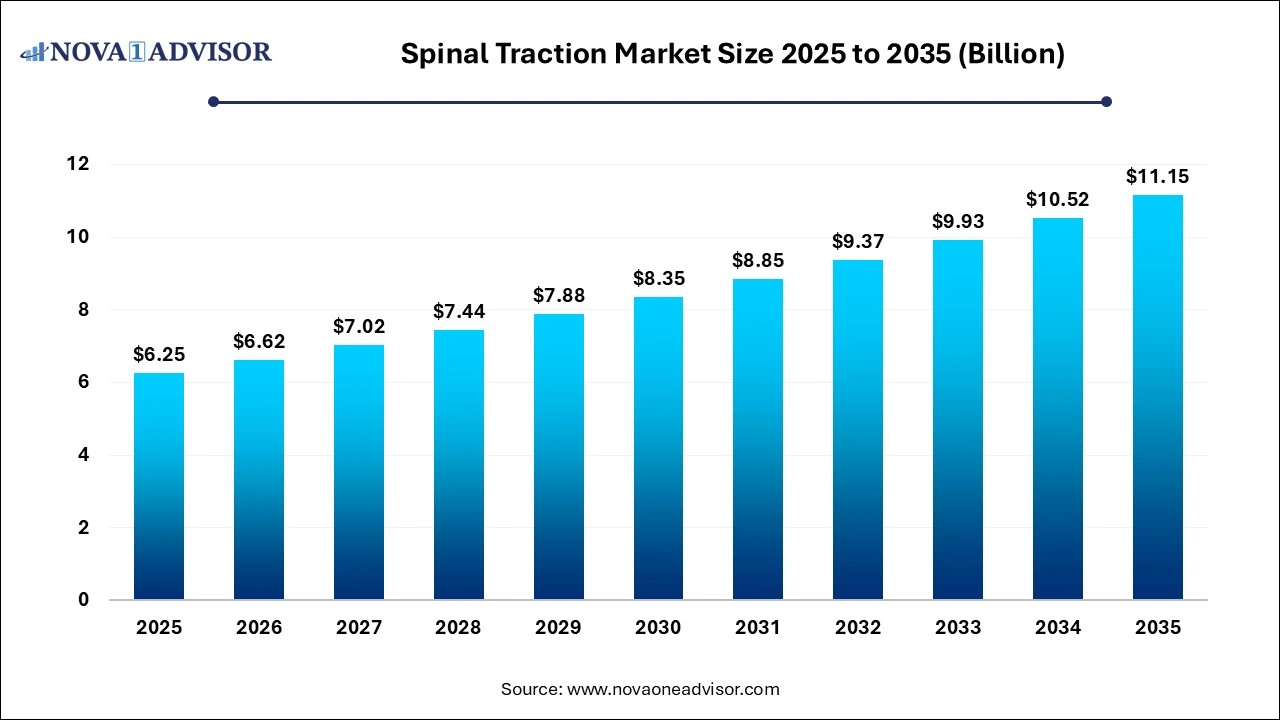
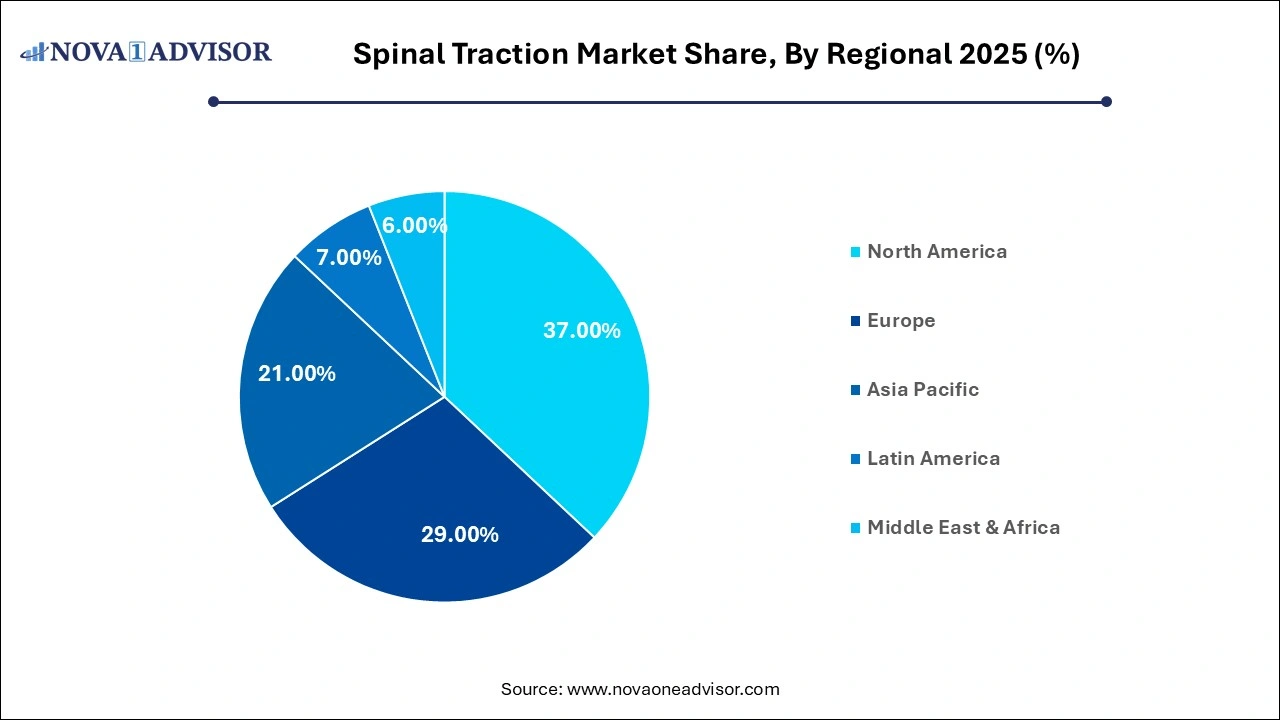
The global spinal traction market size was valued at USD 6.25 billion in 2025 and is projected to grow from USD 6.62 billion in 2026 to USD 11.15 billion by 2035, at a CAGR of 5.96% from 2026 to 2035. North America dominated the market, accounting for a revenue share of 37.0% in 2025.
Key Takeaway
- By type, the mechanical spinal traction segment dominated the market with the largest share in 2025.
- By type, the manual spinal traction segment is expected to grow at the fastest CAGR over the forecast period.
- By applications, the herniated discs segment dominated the market with the largest share in 2025.
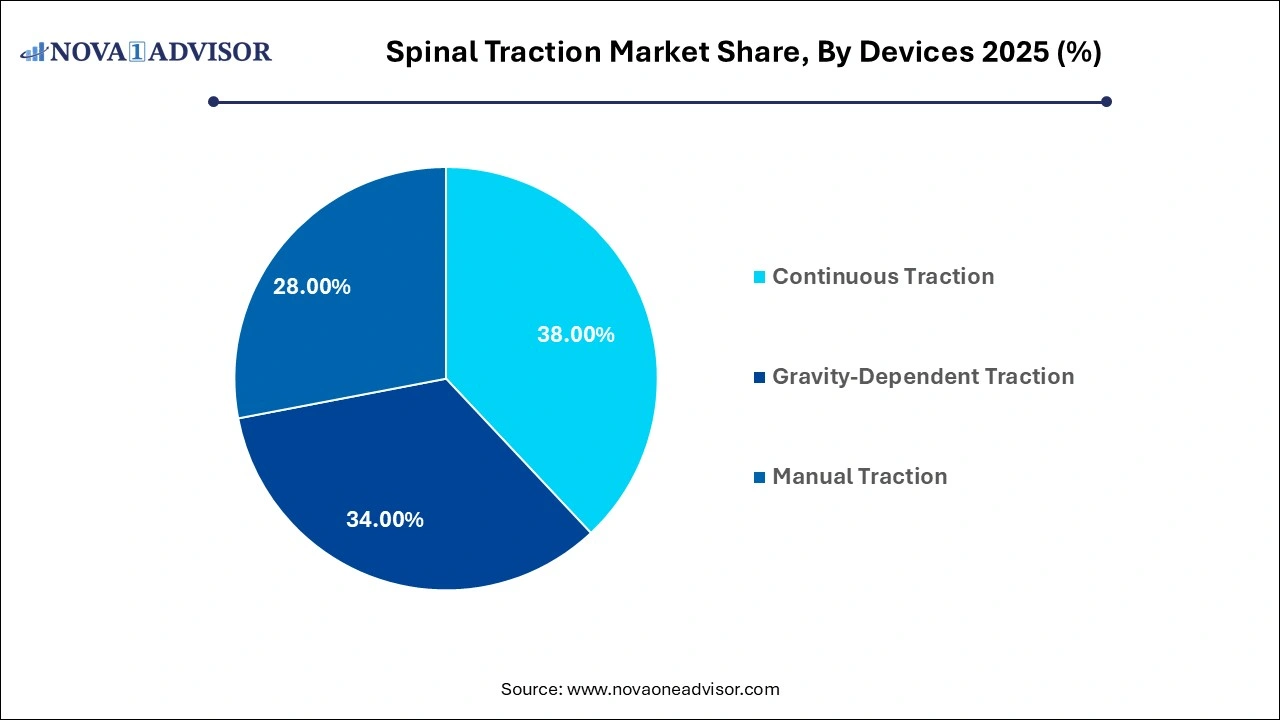
- By devices, the continuous traction segment dominated the market with the largest share Of 38.0% in 2025.
- By region, North America dominated the market with the largest share of 37.0% in 2025.
Market Overview
The global spinal traction market includes traction tables, mechanical and manual systems, accessories, and related technologies designed to apply controlled forces to the spine. Modern systems offer programmable control over force, duration, angle, cycling, and patient positioning, supporting more standardized treatment in clinical settings.
The market is linked to the substantial global burden of musculoskeletal disorders. However, the addressable traction population is narrower than the overall back-pain population because clinical guidelines do not recommend routine traction for nonspecific chronic low back pain. This is encouraging manufacturers and providers to focus on targeted patient selection and multimodal rehabilitation.
Professional systems are widely used across physical therapy clinics, chiropractic practices, rehabilitation centers, hospitals, and specialized spine facilities, while home-use products serve selected consumer applications. Technological development is adding electronic force control, programmable protocols, ergonomic designs, and digital monitoring.
Overall, the spinal traction market is evolving as a specialized rehabilitation-equipment segment, with growth shaped by musculoskeletal disease prevalence, clinical evidence, practitioner adoption, reimbursement, and integration with exercise and other rehabilitation therapies.
Market Outlook
- Market Growth Overview: The global spinal traction market is expected to grow significantly between 2025 and 2035, driven by the increasing incidence of spinal disorders across the globe.
- Sustainability Trends: Sustainability trends involve growing utilisation of sustainable and biocompatible materials.
- Major Investors: Major investors in the market include Medtronic, Stryker Corporation, Zimmer Biomet, DJO Global, BTL International, Hill-Rom Holdings, and Chinesport S.p.a.
How is AI Impacting The Global Spinal Traction Market?
AI is emerging as a decision-support and personalization technology in the spinal traction market. AI can analyze patient information, symptoms, functional assessments, treatment history, and imaging data to help clinicians identify appropriate rehabilitation pathways.
AI-powered imaging can also assist with vertebral segmentation, disc-level identification, and spinal stenosis assessment, potentially supporting more informed treatment planning. Future traction systems could use patient response, tolerance, and previous treatment data to personalize force, duration, angle, and treatment cycles.
Connected traction tables may further integrate force and movement sensors with AI-based monitoring, allowing treatment parameters to be adjusted within predefined clinical limits based on patient response. AI can also track outcomes by combining pain scores, mobility measures, and treatment-session data.
Beyond clinical applications, AI can support predictive equipment maintenance, automated documentation, scheduling, and equipment utilization. Overall, AI is likely to have an incremental impact on the market, with the greatest opportunities in personalized treatment, intelligent monitoring, clinical decision support, and rehabilitation workflow automation.
Spinal Traction Market Report Scope
| Report Coverage | Details |
| Market Size in 2026 | USD 6.62 Billion |
| Market Size by 2035 | USD 11.15 Billion |
| Growth Rate From 2026 to 2035 | CAGR of 5.96% |
| Base Year | 2025 |
| Forecast Period | 2026 to 2035 |
| Segments Covered | By Type, By Applications, By Devices, By Region |
| Market Analysis (Terms Used) | Value (USD Million/Billion) or (Volume/Units) |
| Regional Scope | North America; Europe; Asia Pacific; Central and South America; the Middle East and Africa |
| Key Companies Profiled | Saunders Group, Inc., Scrip, Inc., BTL, Stoll Medizintechnik GmbH, Hill Laboratories Company, North American Medical (NAM) Corporation, Spinetronics, LLC, Dentsply International, Medtronic, Inc., SpineRx Technology, Spinal Designs International, Inc., CERT Health Sciences, LLC and VAX-D Medical Technologies, LLC., and others |
Market Driver – Rising Burden of Spinal and Musculoskeletal Disorders
The growing burden of low back pain and musculoskeletal disorders is supporting demand for spinal rehabilitation equipment. Aging populations, sedentary lifestyles, occupational strain, obesity, and physical inactivity contribute to spinal and musculoskeletal problems. However, traction represents a targeted treatment modality rather than a solution for all back-pain patients, making patient selection and evidence-based applications increasingly important.
Market Restraint – Inconsistent Clinical Evidence and Guideline Limitations
Limited evidence for routine traction use remains a key market restraint. Major clinical guidelines do not recommend traction as a routine treatment for chronic primary low back pain, which can influence referrals, reimbursement, and adoption. Competition from exercise therapy, manual therapy, education, and other conservative treatments further increases the need for manufacturers to demonstrate clear clinical value in specific patient groups.
Market Opportunity – Smart and Personalized Traction Systems
Sensor-enabled and personalized traction systems offer an emerging growth opportunity. Connected equipment can monitor force, positioning, movement, treatment duration, and patient response, creating more standardized treatment records. AI could further analyze session data and support individualized settings within clinically defined parameters, while specialized systems for pediatric and other targeted populations could create additional market segments.
Segmental Insights
By Type
Why did the mechanical spinal traction segment dominate the global spinal traction market?
The mechanical spinal traction segment dominated the market with the largest share in 2025. The dominance of the segment can be attributed to its ease of use, precision and extensive adoption in clinical and homecare settings. In addition, the expansion of physical therapy facilities and specialised chiropractic practices has significantly enhanced the availability and clinical utilisation of mechanical traction devices.
How did the manual spinal traction segment expected to hold the significantly growing global spinal traction market in the coming years?
The manual spinal traction segment is expected to grow at the fastest CAGR over the forecast period. The growth of the segment can be credited to its portability, affordability and ease of use in outpatient and homecare settings. Manual techniques eliminate the need for heavy machinery, which makes them highly suitable for small clinics, budget-constrained facilities, and developing regions, leading to segment growth shortly.
By Applications
Why did the herniated discs segment dominate the global spinal traction market?
The herniated discs segment dominated the market with the largest share in 2025. The dominance of the segment can be linked to the increasing incidence of disc herniation globally and its effectiveness in relieving nerve compression and pain. Additionally, the transition to advanced high-field spine MRI systems has expanded access to diagnostic imaging, improving the early and precise detection of soft tissue disc herniations and growing patient referrals for targeted interventions.
How did the sciatica segment expected to hold the significantly growing global spinal traction market in the coming years?
The sciatica segment is expected to grow at the fastest CAGR over the forecast period. The growth of the segment can be driven by the growing prevalence of nerve compression and associated lower back pain globally coupled with a surge in adoption of home-based traction devices. Contemporary mechanical traction systems use computerised, precision-guided decompression technology to significantly enhance therapeutic efficacy and patient outcomes.
By Devices
Why did the continuous traction segment dominate the global spinal traction market?
The continuous traction segment dominated the market with the largest share in 2025. The dominance of the segment is owing to its ability to offer controlled and uninterrupted spinal decompression over extended periods and extensive use in hospitals. Furthermore, portable and ergonomic continuous traction devices allow the effective administration of reliable therapeutic interventions within home care settings and outpatient physical therapy clinics.
How did the gravity-dependent traction segment expected to hold the significantly growing global spinal traction market in the coming years?
The gravity-dependent traction segment is expected to grow at the fastest CAGR over the forecast period. The growth of the segment is due to its simplicity, low cost and ease of use for outpatient and home care settings. Moreover, patients prefer portable, over-the-door, or frame-based gravity traction devices for the self-administered management and relief of lower back discomfort.
By Region
Why did the North American region account for the largest share of the global spinal traction market?
North America dominated the market with the largest share in 2025. The dominance of the region can be attributed to the increasing incidence of back and musculoskeletal disorders and favourable insurance reimbursement policies. In addition, manufacturers are introducing advanced spinal traction systems featuring digital interfaces for real-time monitoring. These technological enhancements enable clinicians to customise rehabilitation protocols and deliver precise, computerised adjustments.
U.S. Global Spinal Traction Market Trends
The growth of the market in the country can be driven by the increasing inclination towards non-invasive physical therapy alternatives and the surge in lifestyle-related spinal complications. Also, advanced outpatient clinics and specialised physical therapy centres are rapidly adopting modern mechanical traction equipment.
Why did the Asia-Pacific region become the fastest-growing global spinal traction market during the forecast period?
Asia Pacific is expected to grow at the fastest CAGR over the forecast period. The growth of the region can be credited to the growing urbanisation, increasing incidence of spinal disorders and growing healthcare access in major countries like China, Japan, and India. Furthermore, developing nations in the Asia-Pacific region experience a high incidence of road traffic collisions and industrial accidents, which generate a significant volume of acute spinal cord injuries.
China Global Spinal Traction Market Trends
The market in the country is growing due to a surge in ageing population, increasing incidence of desk-job lifestyles and ongoing growth of local medical device manufacturing capabilities. Also, the increasing adoption of non-invasive physical therapy and home-based rehabilitation frameworks has significantly fuelled the market demand for both mechanical and manual traction devices.
Key Players in the Global Spinal Traction Market
- Hill-Rom Holdings / Hillrom: It provides specialised hospital beds, surgical tables, and integrated traction and patient positioning accessories.
- Medtronic & Zimmer Biomet: Major multinational med-tech giants that anchor the broader spinal care, surgical, and implant ecosystems.
- Minato Medical Science & Anyang Xiangyu Medical: Dominant equipment manufacturers scaling rapidly in Asian and international medical rehabilitation markets.
Recent Developments
- In May 2026, Empirical Spine has announced the official U.S. market launch of the LimiFlex Dynamic Sagittal Tether™, an outpatient, motion-preserving alternative to traditional spinal fusion procedures following decompression surgery. Dr Todd Alamin, co-founder of Empirical Spine, successfully performed the first two commercial implantations of the Class III dynamic stabilisation device.
Segments Covered in the Report
This report forecasts revenue growth at country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2035. For this study, Nova one advisor, Inc. has spinal traction market.
By Type
- Manual Spinal Traction
- Mechanical Spinal Traction
By Applications
- Slipped Discs
- Bone Spurs
- Degenerative Disc Disease
- Herniated Discs
- Facet Disease
- Sciatica
- Foramina Stenosis
- Pinched Nerves
By Devices
- Continuous Traction
- Gravity-Dependent Traction
- Manual Traction
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East & Africa (MEA)
FAQ's

Proceed to Buy
Instant PDF delivery on confirmation
 Request Customization
 Download Sample
Get a Sample of this Report
Spinal Traction Market