Allogeneic Cell Therapy Market Size, Share, and Trends 2026 to 2035
 Status Published
 Category Healthcare


Content
Allogeneic Cell Therapy Market Size and Trends
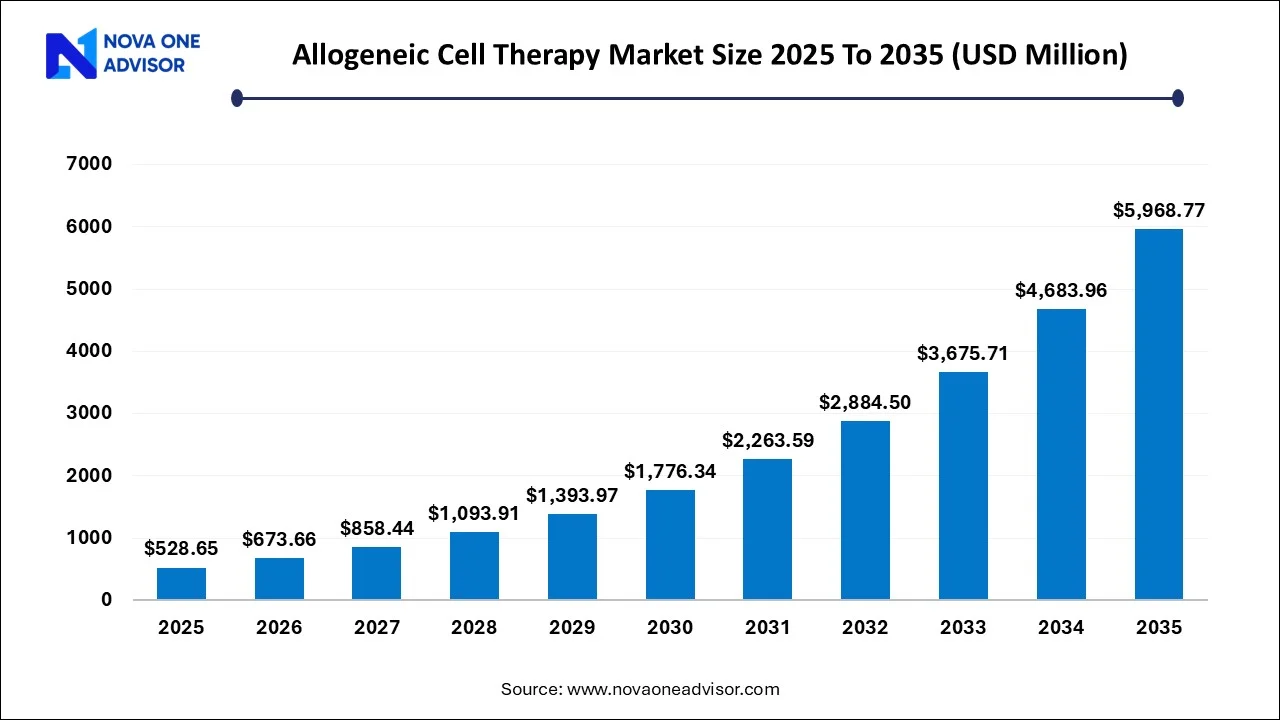
The allogeneic cell therapy market size was exhibited at USD 673.66 million in 2026 and is projected to hit around USD 5968.77 million by 2035, growing at a CAGR of 24.38% during the forecast period 2026 to 2035.
Allogeneic Cell Therapy Market Key Takeaways:
- Based on the therapy type, the stem cell therapies segment dominated the market with the largest share of 77% in 2025.
- The non-stem cell therapies segment is expected to grow at the fastest CAGR of 31.32% by 2035
- The hematological disorders segment accounted for the largest market share of 59.0% in 2025.
- The market is also anticipated to experience profitable growth during the forecast period.
- North America accounted for the largest market share of 81.0% in 2025
- The Europe region is expected to see a significant growth rate in the market from 2026 to 2035.
The growing incidence of chronic diseases such as cancer, cardiovascular diseases, autoimmune disorders, and genetic diseases is expected to drive the growth of the allogeneic cell therapy industry. According to estimates published by the American Cancer Society, 1.9 million new cancer cases were diagnosed in the U.S. alone in 2024, resulting in over 609,000 deaths. Moreover, the aging population worldwide is expected to contribute to a further increase in the global burden of chronic diseases. These factors indicate the critical need for advanced medical treatments, such as allogeneic cell therapy, to treat chronic diseases and improve patient outcomes.
The COVID-19 pandemic had an unfavorable impact on the allogeneic cell therapy industry, causing a decline in research and development activities. This disrupted various processes, including research, clinical trials, manufacturing, and logistics, ultimately affecting the quality of clinical evidence for cell and gene therapies. As a result, evaluating the treatment benefits and economic impacts of these therapies has become more challenging.
However, the pandemic has also raised awareness about the use of cell therapy as a potential treatment option for COVID-19. This increasing awareness is expected to have a positive impact on the market in the coming years. For instance, in May 2020, Lineage Cell Therapeutics received USD 5 million in emergency funding from the California Institute for Regenerative Medicine (CIRM) to develop a potential vaccine against SARS-CoV-2 using VAC, their allogeneic dendritic cell therapy.
Furthermore, the increasing need for advanced medical treatments for chronic diseases has led to a surge in clinical trials for cell therapies. According to data published by ClinicalTrials.gov, as of April 2021, there were 1,358 active cell therapy trials, representing a 43% increase from 2020 to 2021, compared to a 24% increase from 2019 to 2020. The majority of this growth has been due to CAR-T cell clinical trials, which have increased by 83%.
Moreover, there has been a shift in the focus of clinical trials from autologous to allogeneic cell therapy, with many companies conducting clinical trials on allogeneic cell therapy candidates for various diseases, such as cancer, genetic disorders, and autoimmune diseases. This trend is expected to continue, as there is increasing interest from governments, private organizations, and biotechnology companies in the development of allogeneic cell therapies.
Furthermore, the allogeneic cell therapy industry is expected to grow due to the increasing investments in research and development by governments and private & public organizations. For instance, in November 2024, the California Institute for Regenerative Medicine (CIRM) Board awarded over USD 6 million to Jianhua Yu at the Beckman Research Institute of City of Hope for developing a new approach to target hypoxia metastatic breast tumors with allogeneic off-the-shelf anti-EGFR CAR NK cells. This approach aims to improve the efficacy and safety of cancer therapy.
The market is also supported due to the increasing acceptance of cell therapy products by regulatory bodies. For instance, In January 2023, Sana Biotechnology, Inc. received clearance from the FDA to initiate a first-in-human study of SC291, a CD19-targeted allogeneic CAR T cell therapy, in patients with B-Cell malignancies. Additionally, in August 2024, the EMA approved Charles River to commercially produce and distribute allogeneic cell therapy drug products in Europe. These regulatory approvals indicate the growing acceptance of allogeneic cell therapy products as viable treatment options for patients with chronic diseases.
How AI Is Impacting the Global Allogeneic Cell Therapy Market
Artificial intelligence is becoming an important supporting technology in the allogeneic cell therapy market by helping researchers interpret biological data, optimize cell manufacturing, improve quality assurance, and identify promising therapeutic candidates. Allogeneic cell products are derived from donor cells and may be produced in larger batches for multiple recipients. Consequently, manufacturers must maintain consistent cell identity, viability, potency, purity, and safety across production runs. AI-based analytical systems can help identify relationships between donor characteristics, culture conditions, processing parameters, and final product performance. By combining historical manufacturing records with laboratory measurements, developers can investigate which variables are associated with reliable production outcomes.
One important application is donor selection and cell characterization. Machine learning models can help analyze donor screening information, cellular phenotypes, genetic characteristics, and laboratory measurements to identify patterns associated with desired product attributes. These tools may support the assessment of donor-derived hematopoietic stem cells, mesenchymal stromal cells, and immune cell populations. However, clinical eligibility and donor compatibility must continue to be determined through validated medical and laboratory procedures.
AI can also support manufacturing process optimization. Cell expansion, culture duration, nutrient availability, oxygen levels, temperature, and other process parameters can influence cellular behavior. Predictive models may help identify combinations of conditions associated with improved yield and consistent product characteristics. In automated manufacturing facilities, AI-supported monitoring may detect deviations in cell growth or equipment performance earlier, allowing operators to investigate potential quality issues before a batch is released.
Another emerging application involves quality control and image analysis. Computer vision systems can assess cell morphology and growth patterns, while analytical algorithms can help interpret flow cytometry, microscopy, and molecular assay data. These applications may reduce repetitive manual assessment and improve the speed of data interpretation. Nevertheless, AI-generated findings must be verified using validated methods, especially when they influence decisions about product release or patient treatment.
In clinical development, AI can assist with patient stratification, clinical trial recruitment, endpoint analysis, and the identification of potential safety signals. For example, researchers investigating donor-derived immune cell therapies may use analytical models to explore relationships between cellular characteristics, treatment response, immune complications, and disease outcomes. Such insights can help generate hypotheses for prospective clinical validation rather than replace clinical evidence.
Digital manufacturing systems and digital twins may further improve production planning by simulating the effects of changes in culture conditions, equipment utilization, or processing schedules. For commercial manufacturers, better forecasting can help coordinate donor material availability, manufacturing capacity, storage, and distribution.
Despite these opportunities, AI adoption faces several limitations. Cell therapy datasets can be small, inconsistent, and difficult to combine across laboratories. Models trained on one cell product or manufacturing platform may not generalize to another. Data integrity, cybersecurity, explainability, validation, and regulatory compliance remain essential. Therefore, AI is best viewed as an enabling technology that can improve selected stages of research and production rather than a substitute for biological expertise, clinical trials, or regulatory oversight.
Report Scope of Allogeneic Cell Therapy Market
| Report Coverage | Details |
| Market Size in 2026 | USD 673.66 Million |
| Market Size by 2035 | USD 5968.77 Million |
| Growth Rate From 2026 to 2035 | CAGR of 24.38% |
| Forecast Period | 2026-2035 |
| Segments Covered | Therapy Type, Therapeutic Area, Region |
| Market Analysis (Terms Used) | Value (US$ Million/Billion) or (Volume/Units) |
| Regional scope | North America, Europe, Asia Pacific, Latin America, MEA |
| Key Companies Profiled | SSM Cardinal Glennon Children's Medical Center; Cleveland Cord Blood Center; Duke University School of Medicine; New York Blood Center; Clinimmune Labs; University of Colorado Cord Blood Bank; MD Anderson Cord Blood Bank; LifeSouth Community Blood Centers, Inc.; Bloodworks Northwest; JCR Pharmaceuticals Co., Ltd.; Sumitomo Pharma Co., Ltd.; Atara Biotherapeutics; Mallinckrodt Pharmaceuticals; Tego Science Inc; Takeda Pharmaceutical Company Limited; STEMPEUTICS RESEARCH PVT LTD; Biosolution Co., Ltd.; MEDIPOST Co., Ltd. |
Market Driver
Increasing demand for advanced treatments for hematological disorders and other serious diseases
The increasing need for effective treatments for hematological malignancies, bone marrow disorders, immune deficiencies, and other serious diseases is a major driver of the allogeneic cell therapy market. Conventional treatments such as chemotherapy, radiation, immunosuppressive medication, and supportive care can be effective in many clinical settings, but some patients experience relapse, treatment resistance, or persistent disease. Allogeneic cell therapies offer an alternative approach in selected cases by introducing donor-derived cells capable of restoring blood-forming function, modulating immune responses, or targeting diseased cells.
Hematopoietic stem cell transplantation illustrates the clinical importance of donor-derived cellular treatment. Transplanted stem cells can establish new blood-forming and immune systems following appropriate conditioning. In certain blood cancers, donor-derived immune cells can also recognize and attack malignant cells, creating a graft-versus-leukemia effect. This therapeutic potential supports continued investment in transplantation procedures, donor registries, cell processing, and improved approaches to managing transplant-related complications.
Demand is also being shaped by advances in cellular engineering. Developers are investigating allogeneic CAR T-cell products that can be manufactured from donor cells rather than prepared individually from each patient's cells. If clinical studies establish reliable efficacy and acceptable safety, these products could reduce some logistical barriers associated with personalized cell manufacturing. They may also enable centralized production and distribution across specialist treatment centers.
The opportunity extends to regenerative medicine. For example, donor-derived skin cells can be used in selected wound-care applications, while mesenchymal stromal cells are being investigated for their immunomodulatory and tissue-repair potential. These applications create additional research and commercialization pathways beyond hematological disease.
However, rising disease burden alone does not guarantee market growth. Adoption depends on clinical outcomes, treatment affordability, regulatory approval, reimbursement, specialist capacity, and the availability of suitable donor material. The strongest commercial opportunities are likely to emerge where a therapy demonstrates meaningful benefits over existing treatments and can be manufactured consistently at a sustainable cost.
Market Restraint
Immune incompatibility and complex manufacturing requirements
Immune incompatibility and manufacturing complexity represent significant restraints on the allogeneic cell therapy market. Because these treatments use cells from another individual, the recipient's immune system may recognize the transplanted cells as foreign and eliminate them. In hematopoietic stem cell transplantation, donor immune cells can also attack healthy recipient tissues, leading to graft-versus-host disease. These complications can increase treatment burden, require intensive monitoring, and affect patient outcomes.
In engineered allogeneic immune cell therapies, developers face a related challenge: donor-derived cells must remain active long enough to produce a therapeutic effect without triggering unacceptable immune reactions. Researchers are investigating gene editing, immune-evasion strategies, and modifications to cellular receptors to address these issues. Nevertheless, such modifications may introduce additional biological risks and require extensive preclinical and clinical evaluation.
Manufacturing presents a separate barrier. Cell products are biologically complex, and their characteristics may vary according to donor, starting material, culture conditions, processing methods, and storage duration. Companies must establish reproducible production protocols, validated analytical tests, contamination controls, and robust batch-release criteria. These requirements can increase capital expenditure, operating costs, and development timelines.
Storage and distribution also require specialized infrastructure. Temperature excursions, delays, and unsuitable handling conditions can compromise product quality. Manufacturers must therefore coordinate production schedules, inventory, transport, and treatment-center readiness.
Finally, regulatory approval requires evidence that a product is safe, effective, consistently manufactured, and suitable for its intended indication. Clinical development may be expensive, particularly for therapies targeting rare diseases or small patient populations. These barriers can delay commercialization and limit competition. Addressing immune-related complications, improving manufacturing consistency, and demonstrating cost-effectiveness will be important for expanding market access.
Market Opportunity
Development of scalable, ready-to-use cellular therapies
The development of scalable, ready-to-use allogeneic cell therapies represents a major opportunity for biotechnology companies. Autologous treatments typically require cells to be collected from individual patients, processed separately, and returned after manufacturing. Although this personalized approach can be clinically valuable, it may create scheduling challenges, manufacturing delays, and high operational costs. Allogeneic platforms offer the potential to manufacture cells in advance, create multiple doses from qualified donor material, and distribute products through established healthcare networks.
One promising area is donor-derived immune cell therapy for cancer. Companies are developing allogeneic CAR T-cell candidates that could be produced centrally and made available to eligible patients without waiting for an individualized manufacturing cycle. Improvements in gene editing, cell expansion, cryopreservation, and immune compatibility could strengthen the commercial potential of this approach. Success will depend on demonstrating that these products achieve meaningful and durable clinical outcomes while maintaining acceptable safety.
Another opportunity lies in the development of standardized mesenchymal stromal cell products. Their immunomodulatory properties have generated interest in inflammatory and immune-mediated conditions. However, researchers must determine which cell sources, manufacturing methods, doses, and treatment schedules produce reproducible benefits for particular indications. Products supported by strong clinical evidence may create opportunities for broader therapeutic use.
Wound care also offers potential for donor-derived keratinocyte- and fibroblast-based products. Chronic wounds, burns, and other skin injuries can require prolonged treatment and specialized clinical management. Cellular products that demonstrate improved wound closure or other meaningful outcomes could help address unmet needs in selected patient groups.
Emerging markets may offer additional opportunities as healthcare infrastructure, clinical research capabilities, and cell-processing facilities expand. Partnerships between biotechnology developers, hospitals, manufacturing providers, and local distributors could support broader access.
To capitalize on these opportunities, companies need to establish commercially viable manufacturing systems, build reliable distribution networks, secure appropriate regulatory approvals, and generate evidence of economic value. The most promising business models will combine strong clinical differentiation with scalable production and sustainable reimbursement.
Allogeneic Cell Therapy Market By Therapy Type Insights
Based on the therapy type, the stem cell therapies segment dominated the market with the largest share of 77% in 2025. The highest market share of the segment is attributed to the increasing incidence of target diseases that can be treated with such therapies. Allogeneic stem cell therapies are most frequently used to treat chronic diseases like blood cancers, leukemia, and lymphoma as well as specialized blood or autoimmune disorders.
- For instance, the Globocan 2020 study states that 19.3 million cancer cases were detected worldwide in 2020, and the majority of those patients received chemotherapy as treatment. Furthermore, it was observed that chemotherapy radiation can harm the patient's stem cells, requiring an allogeneic stem cell transfer. Such factors can boost segment growth in the near future.
The non-stem cell therapies segment is expected to grow at the fastest CAGR of 31.32% by 2035 owing to the exponential growth in the number of CAR-T therapy clinical studies and its higher success rate. Non-stem cell-based allogeneic cell therapies typically involve the isolation of somatic cells from the human body, their propagation, expansion, selection, and administration to patients for therapeutic, preventive, or diagnostic applications. In addition to immune cells like T cells, natural killer (NK) cells, dendritic cells (DCs), and macrophages, non-stem cell-based treatments also use chondrocytes, keratinocytes, fibroblasts, hepatocytes, and pancreatic islet cells. Hence, a wide range of cell types in this segment is likely to boost its growth in the coming years.
Allogeneic Cell Therapy Market By Therapeutic Area Insights
The hematological disorders segment accounted for the largest market share of 59.0% in 2025. The use of allogeneic cell therapy in the treatment of hematological disorders is necessary due to the increasing prevalence of leukemia, lymphoma, and myeloma, among others. Additionally, the key market players are implementing several strategic plans to create cutting-edge allogeneic cell therapies for hematological disease treatment.
For instance, in January 2024, Bristol Myers Squibb and Century Therapeutics collaborated in developing iPSC-derived allogeneic treatments for solid tumors and hematologic malignancies. Similarly, the increasing number of FDA approvals and strategic moves by key market participants are contributing to the segment's largest market share.
The dermatological disorders segment is expected to witness a rapid CAGR by 2035 since there is a wide range of cell-based therapies under development for the treatment of dermatological diseases.
The market is also anticipated to experience profitable growth during the forecast period due to rising awareness of allogeneic stem cell-based therapy products that can be used to treat a wide range of dermatological diseases, including atopic dermatitis, autoimmune skin disorders, skin aging, wound healing, scar therapy, and many others.
Allogeneic Cell Therapy Market By Regional Insights
North America is expected to remain a leading regional market for allogeneic cell therapy, supported by its biotechnology industry, advanced clinical research infrastructure, specialist transplantation centers, and established regulatory pathways for cellular products. The United States plays an important role in the development and commercialization of donor-derived therapies, supported by research institutions, venture investment, pharmaceutical partnerships, and specialized manufacturing facilities. Regulatory milestones for products such as RYONCIL, STRATAGRAFT, and TREGZI demonstrate the range of clinical applications represented in this market. Adoption is also influenced by the availability of specialist physicians, hospital infrastructure, treatment reimbursement, and access to advanced therapeutic procedures. Canada contributes through transplantation services, regenerative medicine research, and clinical collaborations.
North America could continue to offer substantial growth opportunities through engineered cell therapies, improved transplant outcomes, and manufacturing innovation. Biotechnology companies are investing in donor-derived immune cells designed to treat cancer and other serious diseases, while researchers are developing approaches to reduce immune incompatibility and improve cell persistence. The region also benefits from collaborations between academic centers, biotechnology developers, and contract manufacturing organizations. However, high treatment costs, complex reimbursement requirements, clinical development risks, and manufacturing capacity constraints can influence adoption. Commercial success will depend on demonstrating meaningful clinical benefits, establishing reliable supply chains, and expanding access beyond highly specialized treatment centers.
Europe
Europe represents a significant regional market for allogeneic cell therapy, supported by established transplantation programs, academic research institutions, biotechnology companies, and specialist clinical centers. Countries such as Germany, France, the United Kingdom, Italy, and Spain contribute to research and clinical application through their healthcare systems and biomedical research networks. The region has capabilities in hematopoietic stem cell transplantation, cell processing, regenerative medicine, and clinical evaluation of advanced therapies. European regulatory oversight of advanced therapy medicinal products provides a framework for assessing product quality, safety, and efficacy. Market development is influenced by national reimbursement policies, healthcare budgets, manufacturing capacity, and differences in access to specialized treatments between countries.
Cross-border research collaboration and the development of standardized cellular products could support future European market growth. Academic institutions and biotechnology companies are working to improve cell characterization, manufacturing processes, and treatment outcomes. Research into donor-derived immune cells, mesenchymal stromal cells, and tissue-engineered products may create additional opportunities across oncology, transplantation, and regenerative medicine. Nevertheless, commercialization can be affected by lengthy clinical development, complex regulatory requirements, reimbursement negotiations, and the need to establish treatment infrastructure. Companies seeking to expand in Europe must demonstrate clinical value while addressing differences in healthcare purchasing and access across individual countries.
Asia Pacific
Asia Pacific is an important developing market for allogeneic cell therapy, driven by expanding biotechnology capabilities, growing clinical research activity, and increasing investment in advanced medical treatments. China, Japan, South Korea, Australia, and India contribute to the region's evolving cell therapy ecosystem through research institutions, hospitals, biotechnology companies, and specialized manufacturing facilities. Japan has an established regenerative medicine research environment, while China and South Korea have substantial biotechnology development activity. Australia is also an important location for clinical trials and translational research. Market opportunities vary considerably by country because regulatory frameworks, healthcare financing, specialist treatment capacity, and access to advanced therapies are not uniform across the region.
Expansion of local manufacturing and clinical research could make Asia Pacific an important source of future market growth. Domestic cell-processing facilities, partnerships with international developers, and investment in clinical infrastructure may improve the ability to conduct trials and distribute eligible treatments. Countries with established biotechnology clusters may attract additional development and manufacturing projects. India may offer opportunities through its healthcare industry, scientific workforce, and expanding biotechnology ecosystem, although access to specialized cellular treatments remains influenced by affordability, regulatory requirements, and clinical capacity. Future growth will depend on validated clinical evidence, standardized manufacturing, appropriate regulatory oversight, and broader access to qualified treatment centers.
Latin America
Latin America represents an emerging regional opportunity for allogeneic cell therapy, particularly as healthcare institutions strengthen transplantation services, clinical research, and specialized treatment capabilities. Brazil and Mexico are important markets to monitor because of their healthcare infrastructure, medical research activity, and populations requiring treatment for serious diseases. Other countries in the region may also contribute through specialist hospitals and collaborations with international research institutions. Adoption depends on access to donor registries, qualified laboratories, trained clinical teams, reliable transportation systems, and funding for advanced medical procedures. These factors can influence the number of patients who can receive appropriate allogeneic therapies.
Investment in clinical infrastructure and partnerships with established cell therapy developers could support regional market expansion. Collaborations may help improve access to specialized manufacturing, laboratory testing, clinical training, and treatment protocols. Local clinical research could also contribute to understanding patient needs and implementation requirements. However, affordability remains an important challenge, especially for treatments requiring intensive hospital care, sophisticated cell-processing infrastructure, or long-term monitoring. Differences in regulatory requirements and healthcare financing across countries may also complicate commercialization. Market growth will therefore depend on sustainable funding models, stronger clinical capabilities, and evidence that specific treatments deliver sufficient value for healthcare systems.
Middle East and Africa
The Middle East and Africa represent a developing market for allogeneic cell therapy, with opportunities linked to investment in specialized hospitals, medical research, transplantation services, and advanced healthcare infrastructure. Countries such as Saudi Arabia, the United Arab Emirates, Israel, and South Africa contribute through different combinations of biomedical research, specialist treatment facilities, and biotechnology development. Demand may arise from patients requiring treatment for hematological malignancies, bone marrow disorders, and selected conditions that could benefit from donor-derived cellular therapies. However, regional adoption varies widely because healthcare infrastructure, donor availability, treatment affordability, and regulatory capacity differ between countries.
Investment in specialist treatment centers and international clinical partnerships could create future growth opportunities across the region. Hospitals and research institutions may benefit from collaboration with established cell therapy developers to strengthen clinical capabilities, laboratory standards, and staff training. Improvements in donor registries, cell storage, transportation, and treatment coordination could also support access. Nevertheless, high treatment costs and limited specialist capacity in some markets remain significant barriers. The region's long-term development will depend on appropriate regulatory frameworks, sustainable healthcare investment, access to qualified medical professionals, and the ability to deliver complex therapies safely and consistently.
Some of the prominent players in the allogeneic cell therapy market include:
- SSM Cardinal Glennon Children's Medical Center
- Cleveland Cord Blood Center
- Duke University School of Medicine
- New York Blood Center
- Clinimmune Labs, University of Colorado Cord Blood Bank
- MD Anderson Cord Blood Bank
- LifeSouth Community Blood Centers, Inc.
- Bloodworks Northwest
- JCR Pharmaceuticals Co., Ltd.
- Sumitomo Pharma Co., Ltd.
- Atara Biotherapeutics
- Mallinckrodt Pharmaceuticals
- Tego Science Inc
- Takeda Pharmaceutical Company Limited
- STEMPEUTICS RESEARCH PVT LTD
- Biosolution Co., Ltd.
- MEDIPOST Co., Ltd.
Segments Covered in the Report
This report forecasts revenue growth at country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2026 to 2035. For this study, Nova one advisor, Inc. has segmented the allogeneic cell therapy market
By Therapy Type
- Stem Cell Therapies
-
- Hematopoietic Stem Cell Therapies
- Mesenchymal Stem Cell Therapies
- Non-stem Cell Therapies
-
- Keratinocytes & Fibroblast-based Therapies
- Others
By Therapeutic Area
- Hematological Disorders
- Dermatological Disorders
- Others
By Regional
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East and Africa (MEA)
FAQ's

Proceed to Buy
Instant PDF delivery on confirmation
Allogeneic Cell Therapy Market Size to Hit USD 5968.77 Million by 2035
 Request Customization
 Download Sample
Get a Sample of this Report
Allogeneic Cell Therapy Market